| Tenor / Metric | 30 Oct 2026 | 23 Oct 2026 | Weekly Δ |
|---|---|---|---|
| 3-month | 4.16% | 4.22% | –6 bp |
| 6-month | 4.25% | 4.30% | –5 bp |
| 1-year | 4.36% | 4.44% | –8 bp |
| 2-year | 4.56% | 4.69% | –13 bp |
| 5-year | 4.71% | 4.82% | –11 bp |
| 10-year | 4.94% | 5.00% | –6 bp |
| 30-year | 5.31% | 5.33% | –2 bp |
| AaaAaa represents the highest rung of investment-grade corporate debt, indicating top-level creditworthiness and the lowest default risk. More | 6.01% | 6.00% | +1 bp |
| BaaBaa represent the lowest rung of investment-grade corporate debt with moderate credit risk, making them susceptible to higher default risk than Aaa bonds. More | 6.47% | 6.47% | 0 bp |
| HY OAS | 344 bp | 338 bp | +6 bp |
| 5Y5Y5Y5Y forward rate provides a market-implied view of where policy ultimately settles once cyclical forces dissipate. Importantly, it captures the destination of policy rather than its near-term trajectory, and should be interpreted as a structural anchor rather than a tactical signal. More Forward | 2.22% | 2.20% | +2 bp |
| 5Y Breakeven | 2.46% | 2.48% | –2 bp |
| MOVE IndexThe ICE Bank of America U.S. Bond Market Option Volatility Estimate (MOVE) Index measures implied volatility of U.S. Treasury yields, derived from options on Treasuries (primarily 2Y–30Y maturities). It’s commonly called the “VIX for bonds”, but more precisely, it reflects the market’s expectation of how much Treasury yields will move, not bond prices. It is a critical cross-asset signal. More | 100.20 | 103.31 | –3.11 |
Executive Summary
FRONT/BELLY-LED RALLY | MODEST BULL STEEPENER | FEDWATCH REPRICING SOFTENS NEAR-TERM CONVICTION
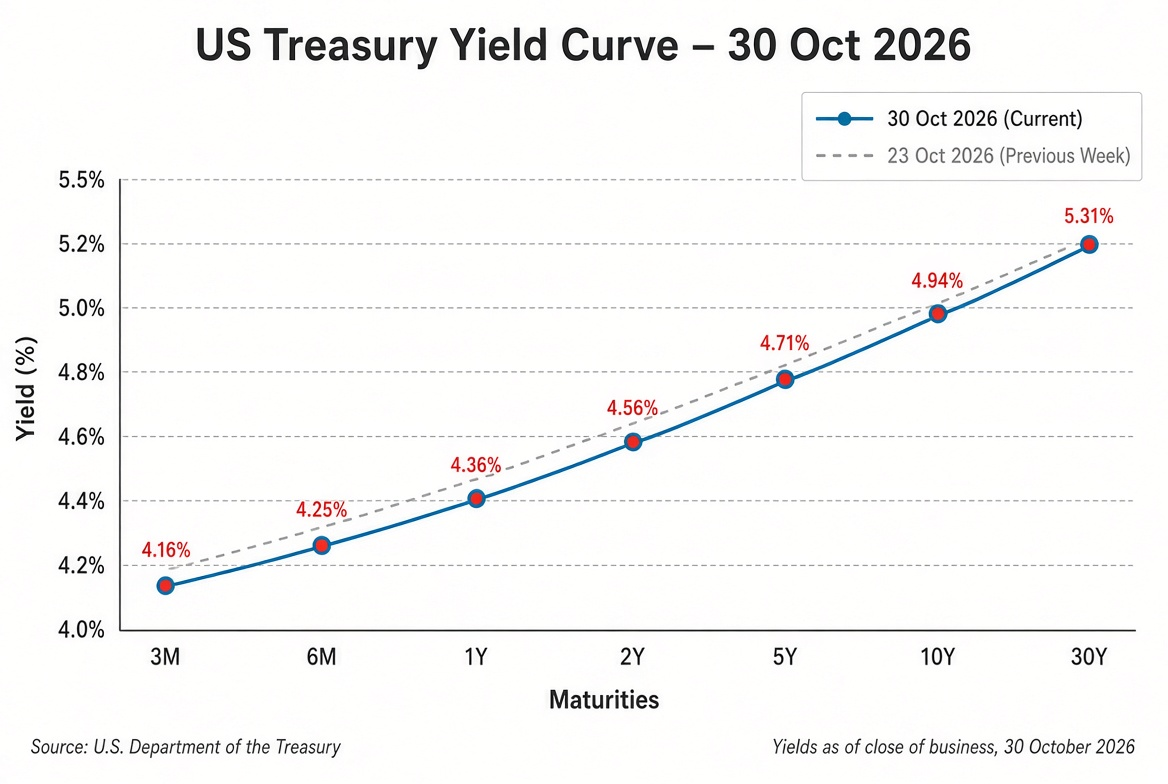
Treasury yields declined across the curve, led by the front end and belly (2Y –13 bp to 4.56%, 5Y –11 bp to 4.71%). The long end was more stable (10Y –6 bp to 4.94%, 30Y –2 bp to 5.31%), producing a modest bull steepenerA bull steepener occurs when short-term rates fall faster than long-term rates and is generally associated with rising recessionary fears. More. Key spreads: 10Y–3M held near +78 bp while 30Y–2Y widened 11 bp to +75 bp. FedWatch saw a sharp reduction in conviction around +25 bp outcomes, most notably a collapse in the January +25 bp probability. Cross-market signals were mixed: HY OAS widened another 6 bp to 344 bp while MOVE eased to 100.20.
Central tension: Front-end relief and reduced near-term hike conviction alongside persistent long-end elevation and further high-yield spread widening.
Curve Decomposition (Front | Belly | Long)
-
-
- Front end (3M–1Y)
3M 4.16% (–6 bp), 6M 4.25% (–5 bp), 1Y 4.36% (–8 bp).
Clear easing. Short-maturity yields declined more than the long end, consistent with the FedWatch shift away from concentrated near-term tightening. - Belly (2Y–5Y)
2Y 4.56% (–13 bp), 5Y 4.71% (–11 bp).
Strongest performance on the curve. Intermediate yields led the rally, reflecting both the reduction in near-term hike probabilities and broader horizon adjustments. - Long end (10Y–30Y)
10Y 4.94% (–6 bp), 30Y 5.31% (–2 bp).
More muted decline. The 10Y remains 44 bp above the 4.50% equity-valuation threshold and well below its recent high of 5.365%. DurationBond Duration: Estimates the percentage change in a bond’s price for every 1% shift in interest rates. For example, a bond with a 3-year duration will gain or lose roughly ±3% of its value if rates fall or rise by 1%. More demand was present but less dominant than in the prior week.
- Front end (3M–1Y)
-
Geometry: Modest bull steepenerA bull steepener occurs when short-term rates fall faster than long-term rates and is generally associated with rising recessionary fears. More. Yields fell across the curve, but the larger declines in the 2Y–5Y sector relative to the 30Y produced a steeper profile.
Policy Path & Inflation Compensation
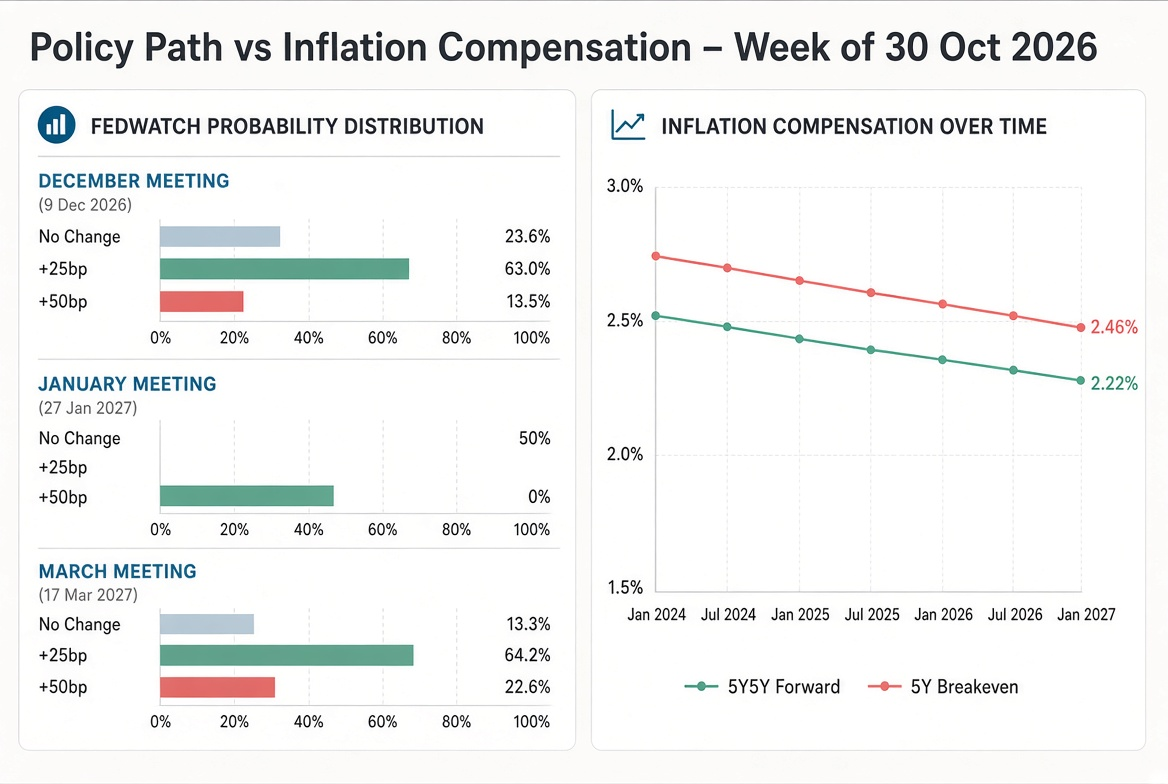
FedWatch distributions lost concentration on single +25 bp hikes:
- December 9: No Change 23.55% | +25 bp 62.98% | +50 bp 13.47%
- January 27: No Change 0% | +25 bp 0% | +50 bp 50%
- March 17: No Change 13.25% | +25 bp 64.20% | +50 bp 22.56%
The largest weekly repricing occurred in January. The path remains tilted toward further tightening overall, but the distribution has become less tightly anchored to small incremental hikes.
Inflation compensation was nearly unchanged: 5Y5Y5Y5Y forward rate provides a market-implied view of where policy ultimately settles once cyclical forces dissipate. Importantly, it captures the destination of policy rather than its near-term trajectory, and should be interpreted as a structural anchor rather than a tactical signal. More forward edged up 2 bp to 2.22% while the 5Y breakeven eased 2 bp to 2.46%. The prior week’s divergence narrowed slightly. The front-end rally is therefore better read as a reduction in near-term policy conviction than a uniform decline in inflation expectations.
Policy Path Clock
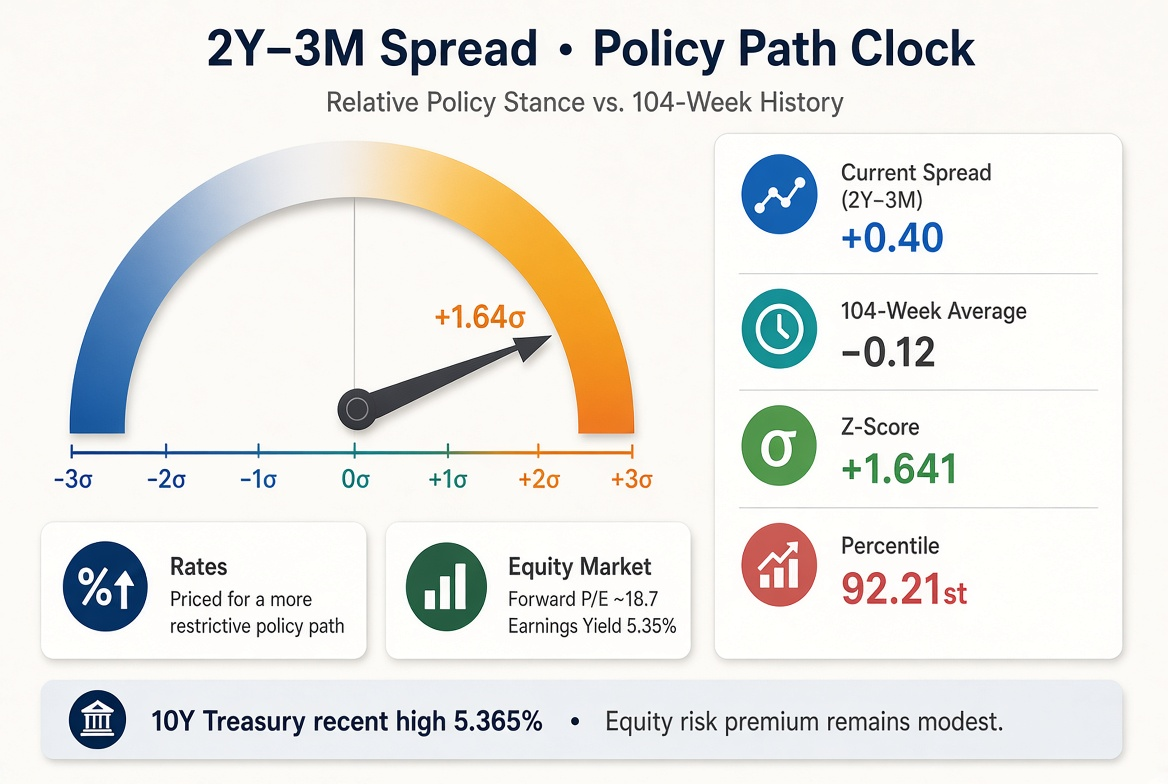
Current 2Y–3M spread: +0.40 (104-week average –0.12; Z-score +1.641; 92.21st percentile).
The spread has eased from the prior week’s +0.47 but remains elevated relative to its two-year history, consistent with a still-restrictive near-term policy configuration even after the front-end rally.
Cross-Market Risk Dashboard
| Signal | Level / Change | Reading |
|---|---|---|
| HY OAS | 344 bp (+6 bp) | Further widening |
| Baa–AaaAaa represents the highest rung of investment-grade corporate debt, indicating top-level creditworthiness and the lowest default risk. More spread | 46 bp (0 bp) | Stable (IG resilient) |
| MOVE IndexThe ICE Bank of America U.S. Bond Market Option Volatility Estimate (MOVE) Index measures implied volatility of U.S. Treasury yields, derived from options on Treasuries (primarily 2Y–30Y maturities). It’s commonly called the “VIX for bonds”, but more precisely, it reflects the market’s expectation of how much Treasury yields will move, not bond prices. It is a critical cross-asset signal. More | 100.20 (–3.11) | Easing but still elevated |
| 2Y / 10Y | –13 / –6 bp | Front/belly led |
The ICE BofA U.S. Bond Market Option Volatility Estimate (MOVE) Index is the primary gauge of expected volatility in the U.S. Treasury market. Often called the "VIX for bonds," it measures market sentiment and interest rate risk by tracking the implied volatility of U.S. Treasury options.
| Date | bp |
|---|---|
| 1/3/2020 | 60.12 |
| 1/10/2020 | 60.12 |
| 1/17/2020 | 53.32 |
| 1/24/2020 | 49.67 |
| 1/31/2020 | 59.94 |
| 2/7/2020 | 72.98 |
| 2/14/2020 | 65.59 |
| 2/21/2020 | 62.38 |
| 2/28/2020 | 74.54 |
| 3/6/2020 | 109.67 |
| 3/13/2020 | 125.21 |
| 3/20/2020 | 138.4 |
| 3/27/2020 | 133.37 |
| 4/3/2020 | 88.33 |
| 4/10/2020 | 65.01 |
| 4/17/2020 | 74.39 |
| 4/24/2020 | 69.84 |
| 5/1/2020 | 66.09 |
| 5/8/2020 | 48.11 |
| 5/15/2020 | 57.4 |
| 5/22/2020 | 56.53 |
| 5/29/2020 | 51.67 |
| 6/5/2020 | 51.55 |
| 6/12/2020 | 61.97 |
| 6/19/2020 | 55.81 |
| 6/26/2020 | 53.45 |
| 7/3/2020 | 51.21 |
| 7/10/2020 | 50.96 |
| 7/17/2020 | 49.19 |
| 7/24/2020 | 45.68 |
| 7/31/2020 | 42.48 |
| 8/7/2020 | 41.98 |
| 8/14/2020 | 41.46 |
| 8/21/2020 | 43.09 |
| 8/28/2020 | 45.14 |
| 9/4/2020 | 48.19 |
| 9/11/2020 | 47.04 |
| 9/18/2020 | 43.12 |
| 9/25/2020 | 37.24 |
| 10/2/2020 | 36.97 |
| 10/9/2020 | 39.97 |
| 10/16/2020 | 57.52 |
| 10/23/2020 | 57.25 |
| 10/30/2020 | 58.46 |
| 11/6/2020 | 61.91 |
| 11/13/2020 | 39.88 |
| 11/20/2020 | 42.95 |
| 11/27/2020 | 42.31 |
| 12/4/2020 | 39.64 |
| 12/11/2020 | 43.89 |
| 12/18/2020 | 47.52 |
| 12/25/2020 | 44.64 |
| 1/1/2021 | 42.11 |
| 1/8/2021 | 48.98 |
| 1/15/2021 | 44.81 |
| 1/22/2021 | 45.14 |
| 1/29/2021 | 43.09 |
| 2/5/2021 | 47.41 |
| 2/12/2021 | 47.2 |
| 2/19/2021 | 47.01 |
| 2/26/2021 | 60.43 |
| 3/5/2021 | 75.66 |
| 3/12/2021 | 69.37 |
| 3/19/2021 | 70.83 |
| 3/26/2021 | 68.8 |
| 4/2/2021 | 61.49 |
| 4/9/2021 | 63.71 |
| 4/16/2021 | 61.21 |
| 4/23/2021 | 62.57 |
| 4/30/2021 | 59.98 |
| 5/7/2021 | 58.13 |
| 5/14/2021 | 54.13 |
| 5/21/2021 | 54.99 |
| 5/28/2021 | 54.59 |
| 6/4/2021 | 52.04 |
| 6/11/2021 | 49.78 |
| 6/18/2021 | 50.85 |
| 6/25/2021 | 60.45 |
| 7/2/2021 | 55.58 |
| 7/9/2021 | 52.41 |
| 7/16/2021 | 59.92 |
| 7/23/2021 | 58.24 |
| 7/30/2021 | 65.28 |
| 8/6/2021 | 61.19 |
| 8/13/2021 | 62.64 |
| 8/20/2021 | 55.45 |
| 8/27/2021 | 59.95 |
| 9/3/2021 | 57.98 |
| 9/10/2021 | 53.26 |
| 9/17/2021 | 51.73 |
| 9/24/2021 | 56.06 |
| 10/1/2021 | 58.46 |
| 10/8/2021 | 57.38 |
| 10/15/2021 | 59.65 |
| 10/22/2021 | 62.7 |
| 10/29/2021 | 72.04 |
| 11/5/2021 | 75.45 |
| 11/12/2021 | 66.9 |
| 11/19/2021 | 78.61 |
| 11/26/2021 | 73.39 |
| 12/3/2021 | 89.45 |
| 12/10/2021 | 79.14 |
| 12/17/2021 | 74.36 |
| 12/24/2021 | 72.46 |
| 12/31/2021 | 77.29 |
| 1/7/2022 | 77.1 |
| 1/14/2022 | 74.69 |
| 1/21/2022 | 76.59 |
| 1/28/2022 | 81.03 |
| 2/4/2022 | 85.29 |
| 2/11/2022 | 87.68 |
| 2/18/2022 | 94.03 |
| 2/25/2022 | 94.36 |
| 3/4/2022 | 93.34 |
| 3/11/2022 | 131.82 |
| 3/18/2022 | 99.03 |
| 3/25/2022 | 91.77 |
| 4/1/2022 | 125.27 |
| 4/8/2022 | 108.34 |
| 4/15/2022 | 124.86 |
| 4/22/2022 | 119.66 |
| 4/29/2022 | 128.12 |
| 5/6/2022 | 128.4 |
| 5/13/2022 | 121.42 |
| 5/20/2022 | 114.61 |
| 5/27/2022 | 111.1 |
| 6/3/2022 | 98.48 |
| 6/10/2022 | 97.73 |
| 6/17/2022 | 114.23 |
| 6/24/2022 | 133.75 |
| 7/1/2022 | 127 |
| 7/8/2022 | 144.17 |
| 7/15/2022 | 145.25 |
| 7/22/2022 | 129.85 |
| 7/29/2022 | 123.7 |
| 8/5/2022 | 116.36 |
| 8/12/2022 | 122.58 |
| 8/19/2022 | 106.28 |
| 8/26/2022 | 123.81 |
| 9/2/2022 | 122.95 |
| 9/9/2022 | 120.72 |
| 9/16/2022 | 121.54 |
| 9/23/2022 | 124.95 |
| 9/30/2022 | 137.28 |
| 10/7/2022 | 141.89 |
| 10/14/2022 | 148.46 |
| 10/21/2022 | 152.89 |
| 10/28/2022 | 156.95 |
| 11/4/2022 | 144.6 |
| 11/11/2022 | 128.44 |
| 11/18/2022 | 111.69 |
| 11/25/2022 | 129.33 |
| 12/2/2022 | 129.6 |
| 12/9/2022 | 118.62 |
| 12/16/2022 | 132.79 |
| 12/23/2022 | 113.65 |
| 12/30/2022 | 113.17 |
| 1/6/2023 | 121.61 |
| 1/13/2023 | 113.87 |
| 1/20/2023 | 113.55 |
| 1/27/2023 | 114.76 |
| 2/3/2023 | 100.7 |
| 2/10/2023 | 98.99 |
| 2/17/2023 | 109.63 |
| 2/24/2023 | 110.11 |
| 3/3/2023 | 122.84 |
| 3/10/2023 | 122.52 |
| 3/17/2023 | 140.06 |
| 3/24/2023 | 180.11 |
| 3/31/2023 | 173.66 |
| 4/7/2023 | 135.93 |
| 4/14/2023 | 139.2 |
| 4/21/2023 | 118.84 |
| 4/28/2023 | 120.84 |
| 5/5/2023 | 122.46 |
| 5/12/2023 | 130.21 |
| 5/19/2023 | 120.52 |
| 5/26/2023 | 127.51 |
| 6/2/2023 | 145.37 |
| 6/9/2023 | 120.95 |
| 6/16/2023 | 115.77 |
| 6/23/2023 | 104.43 |
| 6/30/2023 | 105.74 |
| 7/7/2023 | 110.64 |
| 7/14/2023 | 130.41 |
| 7/21/2023 | 112.48 |
| 7/28/2023 | 106.66 |
| 8/4/2023 | 109.76 |
| 8/11/2023 | 115.91 |
| 8/18/2023 | 112.13 |
| 8/25/2023 | 120.51 |
| 9/1/2023 | 110.37 |
| 9/8/2023 | 102.92 |
| 9/15/2023 | 104.34 |
| 9/22/2023 | 96.61 |
| 9/29/2023 | 101.11 |
| 10/6/2023 | 113.55 |
| 10/13/2023 | 126.64 |
| 10/20/2023 | 128.33 |
| 10/27/2023 | 135.45 |
| 11/3/2023 | 129.16 |
| 11/10/2023 | 118.74 |
| 11/17/2023 | 116.79 |
| 11/24/2023 | 113.11 |
| 12/1/2023 | 107.43 |
| 12/8/2023 | 111.51 |
| 12/15/2023 | 121.65 |
| 12/22/2023 | 115.75 |
| 12/29/2023 | 111.38 |
| 1/5/2024 | 114.62 |
| 1/12/2024 | 116.19 |
| 1/19/2024 | 106.51 |
| 1/26/2024 | 104.97 |
| 2/2/2024 | 100.23 |
| 2/9/2024 | 106.72 |
| 2/16/2024 | 106.21 |
| 2/23/2024 | 109.2 |
| 3/1/2024 | 108.31 |
| 3/8/2024 | 106.48 |
| 3/15/2024 | 100.88 |
| 3/22/2024 | 97.82 |
| 3/29/2024 | 91.04 |
| 4/5/2024 | 86.38 |
| 4/12/2024 | 94.31 |
| 4/19/2024 | 112.82 |
| 4/26/2024 | 111.26 |
| 5/3/2024 | 104.4 |
| 5/10/2024 | 95.96 |
| 5/17/2024 | 94.23 |
| 5/24/2024 | 89.35 |
| 5/31/2024 | 83.57 |
| 6/7/2024 | 91.14 |
| 6/14/2024 | 91.82 |
| 6/21/2024 | 100.16 |
| 6/28/2024 | 94.09 |
| 7/5/2024 | 98.59 |
| 7/12/2024 | 98.78 |
| 7/19/2024 | 86.79 |
| 7/26/2024 | 94.29 |
| 8/2/2024 | 97.76 |
| 8/9/2024 | 112.26 |
| 8/16/2024 | 108.26 |
| 8/23/2024 | 102.81 |
| 8/30/2024 | 105.63 |
| 9/6/2024 | 107.77 |
| 9/13/2024 | 107.24 |
| 9/20/2024 | 100.6 |
| 9/27/2024 | 91 |
| 10/4/2024 | 92.53 |
| 10/11/2024 | 100.15 |
| 10/18/2024 | 118.47 |
| 10/25/2024 | 123.13 |
| 11/1/2024 | 128.4 |
| 11/8/2024 | 132.58 |
| 11/15/2024 | 99.85 |
| 11/22/2024 | 102.47 |
| 11/29/2024 | 99.14 |
| 12/6/2024 | 95.22 |
| 12/13/2024 | 83.2 |
| 12/20/2024 | 85.66 |
| 12/27/2024 | 91.75 |
| 1/3/2025 | 94.8 |
| 1/10/2025 | 93.35 |
| 1/17/2025 | 96.57 |
| 1/24/2025 | 95.6 |
| 1/31/2025 | 86.75 |
| 2/7/2025 | 91.76 |
| 2/14/2025 | 93.13 |
| 2/21/2025 | 84.67 |
| 2/28/2025 | 91.83 |
| 3/7/2025 | 104.46 |
| 3/14/2025 | 104.41 |
| 3/21/2025 | 101.01 |
| 3/28/2025 | 94.54 |
| 4/4/2025 | 96.83 |
| 4/11/2025 | 125.71 |
| 4/18/2025 | 137.26 |
| 4/25/2025 | 114.64 |
| 5/2/2025 | 105.79 |
| 5/9/2025 | 101.4 |
| 5/16/2025 | 100.4 |
| 5/23/2025 | 96.7 |
| 5/30/2025 | 100.91 |
| 6/6/2025 | 92.11 |
| 6/13/2025 | 89.65 |
| 6/20/2025 | 95.31 |
| 6/27/2025 | 90.1 |
| 7/4/2025 | 87.93 |
| 7/11/2025 | 86.09 |
| 7/18/2025 | 85.48 |
| 7/25/2025 | 83.29 |
| 8/1/2025 | 82.09 |
| 8/8/2025 | 83.83 |
| 8/15/2025 | 79.2 |
| 8/22/2025 | 76.66 |
| 8/29/2025 | 78.1 |
| 9/5/2025 | 79.39 |
| 9/12/2025 | 85.29 |
| 9/19/2025 | 73.37 |
| 9/26/2025 | 72.51 |
| 10/3/2025 | 74.38 |
| 10/10/2025 | 69.53 |
| 10/17/2025 | 81.65 |
| 10/24/2025 | 78.62 |
| 10/31/2025 | 68.94 |
| 11/7/2025 | 66.61 |
| 11/14/2025 | 74.41 |
| 11/21/2025 | 79.71 |
| 11/28/2025 | 78.81 |
| 12/5/2025 | 68.95 |
| 12/12/2025 | 67.28 |
| 12/19/2025 | 69.25 |
| 12/26/2025 | 59.41 |
| 1/2/2026 | 58.5 |
| 1/9/2026 | 62.36 |
| 1/16/2026 | 61.55 |
| 1/23/2026 | 58.05 |
| 1/30/2026 | 56.25 |
| 2/6/2026 | 59.2 |
| 2/13/2026 | 63.62 |
| 2/20/2026 | 70.1 |
| 2/27/2026 | 64.27 |
| 3/6/2026 | 73.38 |
| 3/13/2026 | 81.26 |
| 3/20/2026 | 91.17 |
| 3/27/2026 | 108.84 |
| 4/3/2026 | 111.95 |
| 4/10/2026 | 81.78 |
| 4/17/2026 | 72.15 |
| 4./24/2026 | 65.7 |
| 5/1/2026 | 66.97 |
| 5/8/2026 | 70.41 |
| 5/15/2026 | 67.25 |
| 5/22/2026 | 79.87 |
| 5/29/2026 | 78.43 |
| 6/5/2026 | 70.22 |
| 6/12/2026 | 75.2 |
| 6/19/2026 | 69.36 |
| 6/26/2026 | 65.39 |
| 7/3/2026 | 66.79 |
| 7/10/2026 | 65.4 |
| 7/17/2026 | 69.55 |
| 7/24/2026 | 70.88 |
| 7/31/2026 | 76.82 |
| 8/7/2026 | 83.02 |
| 8/14/2026 | 72.03 |
| 8/21/2026 | 69.58 |
| 8/28/2026 | 73.4 |
| 9/4/2026 | 70.97 |
| 9/11/2026 | 73.1 |
| 9/18/2026 | 82.21 |
| 9/25/2026 | 80.64 |
| 10/2/2026 | 96 |
| 10/9/2026 | 107.29 |
| 10/16/2026 | 98.47 |
| 10/23/2026 | 101.1 |
| 10/30/2026 | 103.31 |
| 11/6/2026 | 100.2 |
Investment-grade yields were essentially unchanged while high-yield spreads continued to widen. MOVE declined modestly from the prior week’s elevated level. The configuration remains consistent with selective durationBond Duration: Estimates the percentage change in a bond’s price for every 1% shift in interest rates. For example, a bond with a 3-year duration will gain or lose roughly ±3% of its value if rates fall or rise by 1%. More demand rather than a broad improvement in risk appetite.
Expected 10yr ranges (by timeframe):
| Timeframe | Low (%) | High (%) |
|---|---|---|
| 1 week | 4.80 | 5.08 |
| 1 month | 4.65 | 5.23 |
| 1 year | 3.94 | 5.94 |
Implications & Positioning Lens
The front-end and belly-led decline eases near-term discount-rate pressure more than the long end. The 10Y at 4.94% is 44 bp above the 4.50% equity threshold (improved from 50 bp the prior week) and remains well below the recent high of 5.365%. A forward P/E of 18.7 continues to imply an earnings yield of approximately 5.35%, a modest premium over the 10Y.
However, the further widening in HY OAS to 344 bp and the still-elevated MOVE reading keep the risk backdrop cautious. The FedWatch repricing reduces conviction around incremental near-term hikes but does not shift the overall path toward easing. The combination of front-end relief, stable long-end yields, mixed inflation compensation, and deteriorating high-yield pricing argues for a nuanced reading: policy uncertainty has increased at the margin, but the curve has not yet priced a decisive growth or inflation resolution.
Bottom Line
- Primary signal: Front- and belly-led bull steepenerA bull steepener occurs when short-term rates fall faster than long-term rates and is generally associated with rising recessionary fears. More accompanied by a sharp reduction in FedWatch concentration on +25 bp outcomes.
- Policy: Near-term path remains tilted toward further tightening, but with materially less conviction on the size and timing of the next moves.
- Risk: High-yield spreads widened further while MOVE eased only modestly—still a cautious configuration.
- Unresolved: Whether the front-end rally reflects durable reduction in policy restrictiveness or simply a redistribution of hike probabilities; long-end yields remain elevated relative to equity thresholds.
Positioning bias implied by the data: selective quality durationBond Duration: Estimates the percentage change in a bond’s price for every 1% shift in interest rates. For example, a bond with a 3-year duration will gain or lose roughly ±3% of its value if rates fall or rise by 1%. More remains supported, but high-yield credit continues to warrant caution until spreads stabilize.
Summary Cheat-Sheet Table
| Metric | 30 Oct 2026 | Signal |
|---|---|---|
| Curve regime | Bull steepenerA bull steepener occurs when short-term rates fall faster than long-term rates and is generally associated with rising recessionary fears. More | Front/belly led |
| 10Y–3M spread | +78 bp | Stable |
| 30Y–2Y spread | +75 bp | Steepened |
| 10Y vs 4.50% threshold | +44 bp | Improved but elevated |
| FedWatch next key meeting | Less concentrated | Reduced +25 bp conviction |
| HY OAS | 344 bp | Widening |
| MOVE | 100.20 | Easing but elevated |
| 5Y5Y5Y5Y forward rate provides a market-implied view of where policy ultimately settles once cyclical forces dissipate. Importantly, it captures the destination of policy rather than its near-term trajectory, and should be interpreted as a structural anchor rather than a tactical signal. More / 5Y BEI | 2.22% / 2.46% | Nearly unchanged |
Yield Curve Data
| Date | 3-mth | 6-mth | 1-yr | 2-yr | 5-yr | 10-yr | 30-yr | AaaAaa represents the highest rung of investment-grade corporate debt, indicating top-level creditworthiness and the lowest default risk. More | BaaBaa represent the lowest rung of investment-grade corporate debt with moderate credit risk, making them susceptible to higher default risk than Aaa bonds. More | HY-OAS | 5Y5Y5Y5Y forward rate provides a market-implied view of where policy ultimately settles once cyclical forces dissipate. Importantly, it captures the destination of policy rather than its near-term trajectory, and should be interpreted as a structural anchor rather than a tactical signal. More Forward | 5Y Breakeven Inflation | MOVE IndexThe ICE Bank of America U.S. Bond Market Option Volatility Estimate (MOVE) Index measures implied volatility of U.S. Treasury yields, derived from options on Treasuries (primarily 2Y–30Y maturities). It’s commonly called the “VIX for bonds”, but more precisely, it reflects the market’s expectation of how much Treasury yields will move, not bond prices. It is a critical cross-asset signal. More | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 10/30/2026 | 4.16 | 4.25 | 4.36 | 4.56 | 4.71 | 4.94 | 5.31 | 6.01 | 6.47 | 3.44 | 2.22 | 2.46 | 100.20 | |
| 10/23/2026 | 4.22 | 4.30 | 4.44 | 4.69 | 4.82 | 5.00 | 5.33 | 6 | 6.47 | 3.38 | 2.2 | 2.48 | 103.31 | |
| 10/16/2026 | 4.26 | 4.34 | 4.46 | 4.74 | 4.89 | 5.09 | 5.43 | 6.06 | 6.55 | 3.31 | 2.33 | 2.37 | 101.10 | |
| 10/9/2026 | 4.25 | 4.32 | 4.47 | 4.80 | 5.02 | 5.24 | 5.60 | 6.22 | 6.69 | 3.11 | 2.32 | 2.34 | 98.47 | |
| 10/2/2026 | 4.19 | 4.27 | 4.46 | 4.83 | 5.06 | 5.28 | 5.63 | 6.28 | 6.75 | 3.10 | 2.35 | 2.37 | 107.29 | |
| 9/25/2026 | 4.24 | 4.33 | 4.50 | 4.81 | 4.98 | 5.17 | 5.49 | 6.18 | 6.63 | 2.93 | 2.34 | 2.34 | 96.00 | |
| 9/18/2026 | 4.14 | 4.24 | 4.44 | 4.76 | 4.86 | 5.01 | 5.34 | 5.98 | 6.41 | 2.68 | 2.35 | 2.31 | 80.64 | |
| 9/11/2026 | 4.07 | 4.12 | 4.35 | 4.63 | 4.78 | 4.96 | 5.35 | 6.03 | 6.46 | 2.65 | 2.32 | 2.4 | 82.21 | |
| 9/4/2026 | 3.91 | 3.98 | 4.13 | 4.37 | 4.54 | 4.78 | 5.24 | 5.92 | 6.34 | 2.68 | 2.33 | 2.37 | 73.1 | |
| 8/28/2026 | 3.90 | 4.02 | 4.15 | 4.34 | 4.48 | 4.73 | 5.22 | 5.86 | 6.27 | 2.60 | 2.32 | 2.3 | 70.97 | |
| 8/21/2026 | 3.88 | 3.95 | 4.03 | 4.24 | 4.43 | 4.74 | 5.27 | 5.92 | 6.37 | 2.70 | 2.34 | 2.34 | 73.4 | |
| 8/14/2026 | 3.86 | 3.95 | 3.98 | 4.17 | 4.36 | 4.68 | 5.25 | 5.92 | 6.37 | 2.67 | 2.3 | 2.24 | 69.58 | |
| 8/7/2026 | 3.87 | 3.96 | 4.01 | 4.19 | 4.35 | 4.65 | 5.19 | 5.85 | 6.29 | 2.7 | 2.28 | 2.22 | 72.03 | |
| 7/31/2026 | 3.83 | 3.98 | 4.08 | 4.28 | 4.45 | 4.75 | 5.27 | 5.96 | 6.38 | 2.84 | 2.3 | 2.26 | 83.02 | |
| 7/24/2026 | 3.96 | 4.08 | 4.14 | 4.33 | 4.43 | 4.69 | 5.16 | 5.87 | 6.28 | 2.79 | 2.28 | 2.24 | 76.82 | |
| 7/17/2026 | 3.85 | 3.96 | 4.01 | 4.18 | 4.28 | 4.55 | 5.06 | 5.72 | 6.14 | 2.73 | 2.21 | 2.27 | 70.88 | |
| 7/10/2026 | 3.85 | 3.99 | 4.06 | 4.21 | 4.30 | 4.56 | 5.06 | 5.72 | 6.14 | 2.69 | 2.2 | 2.28 | 69.55 | |
| 7/3/2026 | 3.82 | 3.98 | 3.96 | 4.14 | 4.23 | 4.49 | 4.98 | 5.6 | 6.02 | 2.74 | 2.22 | 2.24 | 65.4 | |
| 6/26/2026 | 3.83 | 3.94 | 3.94 | 4.07 | 4.12 | 4.38 | 4.87 | 5.5 | 5.94 | 2.83 | 2.19 | 2.21 | 66.79 | |
| 6/19/2026 | 3.83 | 3.92 | 4.00 | 4.19 | 4.23 | 4.46 | 4.90 | 5.5 | 5.97 | 2.66 | 2.23 | 2.27 | 65.39 | |
| 6/12/2026 | 3.78 | 3.82 | 3.86 | 4.09 | 4.21 | 4.48 | 4.97 | 5.52 | 6.01 | 2.71 | 2.23 | 2.39 | 69.36 | |
| 6/5/2026 | 3.78 | 3.81 | 3.88 | 4.17 | 4.29 | 4.55 | 5.01 | 5.53 | 6.06 | 2.76 | 2.24 | 2.48 | 75.2 | |
| 5/29/2026 | 3.69 | 3.78 | 3.79 | 3.98 | 4.13 | 4.45 | 4.99 | 5.5 | 6.02 | 2.72 | 2.24 | 2.52 | 70.22 | |
| 5/22/2026 | 3.68 | 3.79 | 3.86 | 4.13 | 4.27 | 4.56 | 5.07 | 5.61 | 6.13 | 2.74 | 2.26 | 2.54 | 78.43 | |
| 5/15/2026 | 3.69 | 3.77 | 3.82 | 4.09 | 4.26 | 4.59 | 5.12 | 5.65 | 6.21 | 2.80 | 2.28 | 2.7 | 79.87 | |
| 5/8/2026 | 3.69 | 3.74 | 3.75 | 3.90 | 4.02 | 4.38 | 4.95 | 5.47 | 6.03 | 2.81 | 2.28 | 2.62 | 67.25 | |
| 5/1/2026 | 3.68 | 3.71 | 3.73 | 3.88 | 4.02 | 4.39 | 4.97 | 5.49 | 6.08 | 2.77 | 2.27 | 2.69 | 70.41 | |
| 4/24/2026 | 3.69 | 3.71 | 3.67 | 3.78 | 3.92 | 4.31 | 4.91 | 5.41 | 6.01 | 2.86 | 2.23 | 2.61 | 66.97 | |
| 4/17/2026 | 3.70 | 3.69 | 3.64 | 3.71 | 3.84 | 4.26 | 4.88 | 5.36 | 5.98 | 2.83 | 2.16 | 2.56 | 65.7 | |
| 4/10/2026 | 3.69 | 3.72 | 3.70 | 3.81 | 3.94 | 4.31 | 4.91 | 5.42 | 6.03 | 2.94 | 2.14 | 2.58 | 72.15 | |
| 4/3/2026 | 3.71 | 3.73 | 3.72 | 3.84 | 3.99 | 4.35 | 4.91 | 5.44 | 6.05 | 3.13 | 2.11 | 2.61 | 81.78 | |
| 3/27/2026 | 3.73 | 3.75 | 3.77 | 3.88 | 4.06 | 4.44 | 4.98 | 5.66 | 6.22 | 3.42 | 2.06 | 2.56 | 111.95 | |
| 3/20/2026 | 3.74 | 3.79 | 3.80 | 3.88 | 4.01 | 4.39 | 4.96 | 5.61 | 6.18 | 3.24 | 2.13 | 2.63 | 108.84 | |
| 3/13/2026 | 3.72 | 3.70 | 3.66 | 3.73 | 3.87 | 4.28 | 4.90 | 5.60 | 6.11 | 3.28 | 2.11 | 2.61 | 91.17 | |
| 3/6/2026 | 3.71 | 3.68 | 3.56 | 3.53 | 3.67 | 4.10 | 4.73 | 5.32 | 5.86 | 3.13 | 2.14 | 2.56 | 81.26 | |
| 2/27/2026 | 3.68 | 3.61 | 3.48 | 3.42 | 3.58 | 4.02 | 4.64 | 5.25 | 5.77 | 3.10 | 2.1 | 2.40 | 73.38 | |
| 2/20/2026 | 3.69 | 3.60 | 3.51 | 3.46 | 3.65 | 4.08 | 4.72 | 5.25 | 5.76 | 2.86 | 2.13 | 2.43 | 64.27 | |
| 2/13/2026 | 3.68 | 3.59 | 3.42 | 3.40 | 3.61 | 4.04 | 4.69 | 5.31 | 5.81 | 2.95 | 2.12 | 2.42 | 70.1 | |
| 2/6/2026 | 3.68 | 3.59 | 3.45 | 3.54 | 3.80 | 4.26 | 4.85 | 5.40 | 5.90 | 2.87 | 2.18 | 2.50 | 63.62 | |
| 1/30/2026 | 3.67 | 3.61 | 3.48 | 3.54 | 3.81 | 4.24 | 4.87 | 5.35 | 5.86 | 2.80 | 2.19 | 2.53 | 59.2 |
Source: Federal Reserve Economic Data (FRED) is an online database created and maintained by the Research Department at the Federal Reserve Bank of St. Louis