| Tenor / Metric | 13 Nov 2026 | 6 Nov 2026 | Weekly Δ |
|---|---|---|---|
| 3-month | 4.32% | 4.19% | +13 bp |
| 6-month | 4.42% | 4.23% | +19 bp |
| 1-year | 4.65% | 4.33% | +32 bp |
| 2-year | 4.88% | 4.51% | +37 bp |
| 5-year | 4.98% | 4.64% | +34 bp |
| 10-year | 5.15% | 4.86% | +29 bp |
| 30-year | 5.47% | 5.26% | +21 bp |
| AaaAaa represents the highest rung of investment-grade corporate debt, indicating top-level creditworthiness and the lowest default risk. More | 6.17% | 5.99% | +18 bp |
| BaaBaa represent the lowest rung of investment-grade corporate debt with moderate credit risk, making them susceptible to higher default risk than Aaa bonds. More | 6.62% | 6.42% | +20 bp |
| HY OAS | 323 bp | 342 bp | –19 bp |
| 5Y5Y5Y5Y forward rate provides a market-implied view of where policy ultimately settles once cyclical forces dissipate. Importantly, it captures the destination of policy rather than its near-term trajectory, and should be interpreted as a structural anchor rather than a tactical signal. More Forward | 2.18% | 2.17% | +1 bp |
| 5Y Breakeven | 2.30% | 2.29% | +1 bp |
| MOVE IndexThe ICE Bank of America U.S. Bond Market Option Volatility Estimate (MOVE) Index measures implied volatility of U.S. Treasury yields, derived from options on Treasuries (primarily 2Y–30Y maturities). It’s commonly called the “VIX for bonds”, but more precisely, it reflects the market’s expectation of how much Treasury yields will move, not bond prices. It is a critical cross-asset signal. More | 98.79 | 92.77 | +6.02 |
Executive Summary
SHARP BELLY-LED SELLOFF | MIXED CURVE GEOMETRY | FEDWATCH LOCKS IN DECEMBER +25 BP
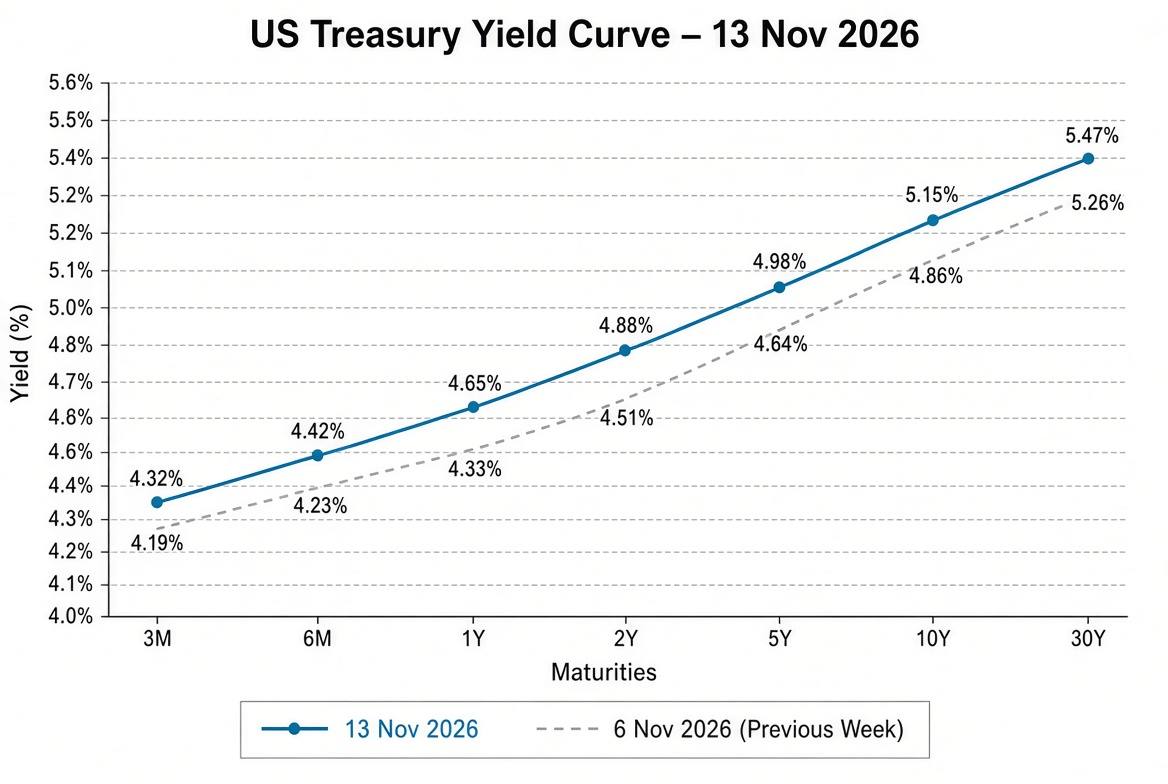
Treasury yields rose sharply across the curve, led by the front end and belly (1Y +32 bp to 4.65%, 2Y +37 bp to 4.88%, 5Y +34 bp to 4.98%). The long end rose less (10Y +29 bp to 5.15%, 30Y +21 bp to 5.47%). Key spreads moved in opposite directions: 10Y–3M widened 16 bp to +83 bp while 30Y–2Y narrowed 16 bp to +59 bp. FedWatch shifted dramatically toward higher near-term rates, with December now concentrated at ~94% on a +25 bp hike. Cross-market signals were mixed: HY OAS improved 19 bp to 323 bp but remains above 300 bp, while MOVE rose to 98.79.
Central tension: Aggressive belly-led sell-off with tighter FedWatch pricing alongside still-elevated high-yield spreads.
Curve Decomposition (Front | Belly | Long)
-
-
- Front end (3M–1Y)
3M 4.32% (+13 bp), 6M 4.42% (+19 bp), 1Y 4.65% (+32 bp).
The front end rose, but less than the belly. The 1-year led this segment, consistent with the near-lock-in of a December hike in FedWatch. - Belly (2Y–5Y)
2Y 4.88% (+37 bp), 5Y 4.98% (+34 bp).
Strongest sell-off on the curve. Intermediate yields drove the move higher, reflecting both the concentrated December hike probability and a broader re-pricing of the near-term path. - Long end (10Y–30Y)
10Y 5.15% (+29 bp), 30Y 5.47% (+21 bp).
More muted increase. The 10Y is now 65 bp above the 4.50% equity-valuation threshold (up from 36 bp) and remains below the recent high of 5.365%.
- Front end (3M–1Y)
-
Geometry: Belly-led bear move with mixed spread changes. Longer-end spreads flattened (30Y–2Y narrowed 16 bp to +59 bp; 30Y–10Y narrowed 8 bp to +32 bp) because the 30Y rose less than the belly. However, the 10Y–3M spread steepened 16 bp to +83 bp because the 3-month rose only +13 bp while the 10Y rose +29 bp. The move is therefore better characterized as a belly-led sell-off with mixed geometry rather than a clean bear flattenerA bear flattener is a yield curve shift where short-term interest rates rise faster than long-term rates and often signals potential economic contraction or slower growth ahead. More.
Policy Path & Inflation Compensation
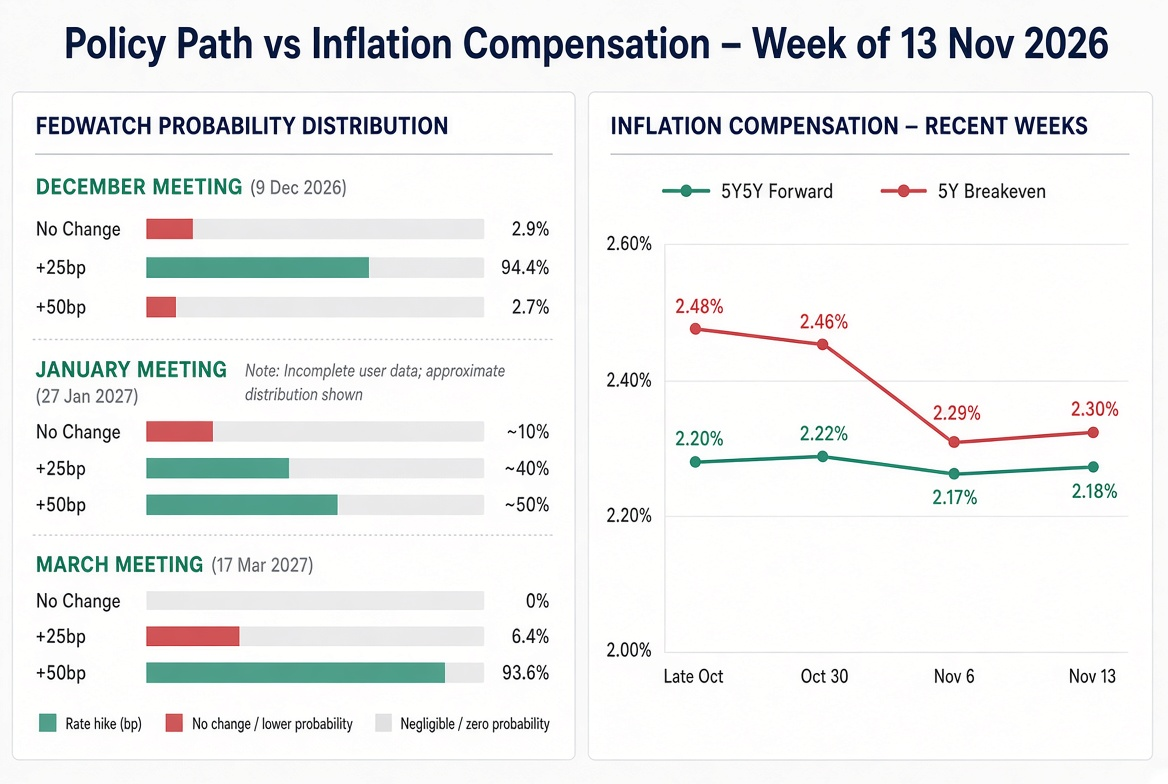
FedWatch distributions shifted decisively toward higher rates:
- December 9: No Change 2.88% | +25 bp 94.41% | +50 bp 2.71%
- January 27: No Change ~8–12% | +25 bp ~35–45% |+50 bp ~45–55%.
- March 17: No Change 0% | +25 bp 6.38% | +50 bp 93.62%
December is now highly concentrated on a +25 bp outcome. Later meetings show increasing probability mass on +50 bp. Inflation compensation was nearly unchanged: 5Y5Y5Y5Y forward rate provides a market-implied view of where policy ultimately settles once cyclical forces dissipate. Importantly, it captures the destination of policy rather than its near-term trajectory, and should be interpreted as a structural anchor rather than a tactical signal. More forward edged up 1 bp to 2.18% and the 5Y breakeven rose 1 bp to 2.30%. The large nominal yield increase is therefore better read as a rise in real rates / policy expectations than a uniform increase in inflation compensation.
Policy Path Clock
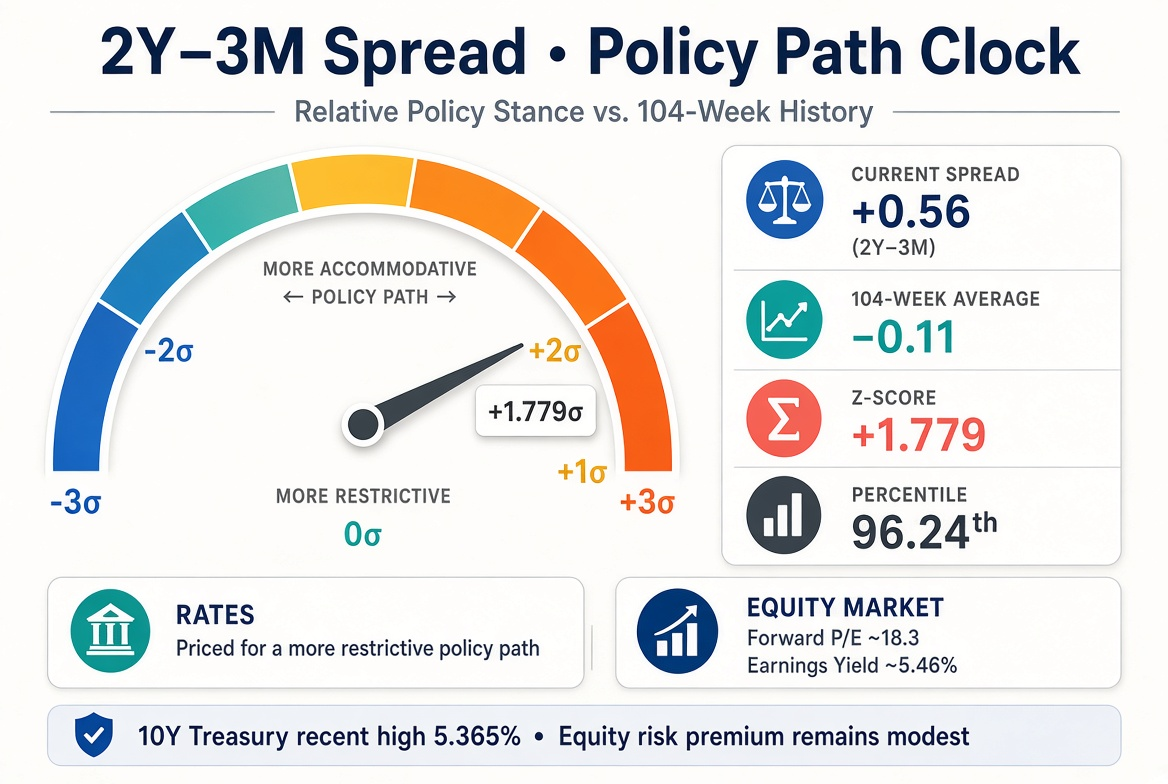
Current 2Y–3M spread: +0.56 (104-week average –0.11; Z-score +1.779; 96.24th percentile).
The spread has widened sharply from the prior week’s +0.32 and is now near the high end of its two-year range, consistent with a more restrictive near-term policy configuration.
Cross-Market Risk Dashboard
| Signal | Level / Change | Reading |
|---|---|---|
| HY OAS | 323 bp (–19 bp) | Improved but still above 300 bp — remains a point of concern |
| Baa–AaaAaa represents the highest rung of investment-grade corporate debt, indicating top-level creditworthiness and the lowest default risk. More spread | 45 bp (+2 bp) | Slight widening (IG stable) |
| MOVE IndexThe ICE Bank of America U.S. Bond Market Option Volatility Estimate (MOVE) Index measures implied volatility of U.S. Treasury yields, derived from options on Treasuries (primarily 2Y–30Y maturities). It’s commonly called the “VIX for bonds”, but more precisely, it reflects the market’s expectation of how much Treasury yields will move, not bond prices. It is a critical cross-asset signal. More | 98.79 (+6.02) | Higher |
| 2Y / 10Y | +37 / +29 bp | Belly-led sell-off |
The ICE BofA U.S. Bond Market Option Volatility Estimate (MOVE) Index is the primary gauge of expected volatility in the U.S. Treasury market. Often called the "VIX for bonds," it measures market sentiment and interest rate risk by tracking the implied volatilityA real-time estimate of how much a stock or asset is expected to move (magnitude not direction) in the future, calculated from current options prices. Unlike historical volatility (which looks backward at past price swings), IV looks forward to reflect market uncertainty. High IV makes options more expensive while low IV makes options cheaper. More of U.S. Treasury options.
| Date | bp |
|---|---|
| 1/3/2020 | 60.12 |
| 1/10/2020 | 60.12 |
| 1/17/2020 | 53.32 |
| 1/24/2020 | 49.67 |
| 1/31/2020 | 59.94 |
| 2/7/2020 | 72.98 |
| 2/14/2020 | 65.59 |
| 2/21/2020 | 62.38 |
| 2/28/2020 | 74.54 |
| 3/6/2020 | 109.67 |
| 3/13/2020 | 125.21 |
| 3/20/2020 | 138.4 |
| 3/27/2020 | 133.37 |
| 4/3/2020 | 88.33 |
| 4/10/2020 | 65.01 |
| 4/17/2020 | 74.39 |
| 4/24/2020 | 69.84 |
| 5/1/2020 | 66.09 |
| 5/8/2020 | 48.11 |
| 5/15/2020 | 57.4 |
| 5/22/2020 | 56.53 |
| 5/29/2020 | 51.67 |
| 6/5/2020 | 51.55 |
| 6/12/2020 | 61.97 |
| 6/19/2020 | 55.81 |
| 6/26/2020 | 53.45 |
| 7/3/2020 | 51.21 |
| 7/10/2020 | 50.96 |
| 7/17/2020 | 49.19 |
| 7/24/2020 | 45.68 |
| 7/31/2020 | 42.48 |
| 8/7/2020 | 41.98 |
| 8/14/2020 | 41.46 |
| 8/21/2020 | 43.09 |
| 8/28/2020 | 45.14 |
| 9/4/2020 | 48.19 |
| 9/11/2020 | 47.04 |
| 9/18/2020 | 43.12 |
| 9/25/2020 | 37.24 |
| 10/2/2020 | 36.97 |
| 10/9/2020 | 39.97 |
| 10/16/2020 | 57.52 |
| 10/23/2020 | 57.25 |
| 10/30/2020 | 58.46 |
| 11/6/2020 | 61.91 |
| 11/13/2020 | 39.88 |
| 11/20/2020 | 42.95 |
| 11/27/2020 | 42.31 |
| 12/4/2020 | 39.64 |
| 12/11/2020 | 43.89 |
| 12/18/2020 | 47.52 |
| 12/25/2020 | 44.64 |
| 1/1/2021 | 42.11 |
| 1/8/2021 | 48.98 |
| 1/15/2021 | 44.81 |
| 1/22/2021 | 45.14 |
| 1/29/2021 | 43.09 |
| 2/5/2021 | 47.41 |
| 2/12/2021 | 47.2 |
| 2/19/2021 | 47.01 |
| 2/26/2021 | 60.43 |
| 3/5/2021 | 75.66 |
| 3/12/2021 | 69.37 |
| 3/19/2021 | 70.83 |
| 3/26/2021 | 68.8 |
| 4/2/2021 | 61.49 |
| 4/9/2021 | 63.71 |
| 4/16/2021 | 61.21 |
| 4/23/2021 | 62.57 |
| 4/30/2021 | 59.98 |
| 5/7/2021 | 58.13 |
| 5/14/2021 | 54.13 |
| 5/21/2021 | 54.99 |
| 5/28/2021 | 54.59 |
| 6/4/2021 | 52.04 |
| 6/11/2021 | 49.78 |
| 6/18/2021 | 50.85 |
| 6/25/2021 | 60.45 |
| 7/2/2021 | 55.58 |
| 7/9/2021 | 52.41 |
| 7/16/2021 | 59.92 |
| 7/23/2021 | 58.24 |
| 7/30/2021 | 65.28 |
| 8/6/2021 | 61.19 |
| 8/13/2021 | 62.64 |
| 8/20/2021 | 55.45 |
| 8/27/2021 | 59.95 |
| 9/3/2021 | 57.98 |
| 9/10/2021 | 53.26 |
| 9/17/2021 | 51.73 |
| 9/24/2021 | 56.06 |
| 10/1/2021 | 58.46 |
| 10/8/2021 | 57.38 |
| 10/15/2021 | 59.65 |
| 10/22/2021 | 62.7 |
| 10/29/2021 | 72.04 |
| 11/5/2021 | 75.45 |
| 11/12/2021 | 66.9 |
| 11/19/2021 | 78.61 |
| 11/26/2021 | 73.39 |
| 12/3/2021 | 89.45 |
| 12/10/2021 | 79.14 |
| 12/17/2021 | 74.36 |
| 12/24/2021 | 72.46 |
| 12/31/2021 | 77.29 |
| 1/7/2022 | 77.1 |
| 1/14/2022 | 74.69 |
| 1/21/2022 | 76.59 |
| 1/28/2022 | 81.03 |
| 2/4/2022 | 85.29 |
| 2/11/2022 | 87.68 |
| 2/18/2022 | 94.03 |
| 2/25/2022 | 94.36 |
| 3/4/2022 | 93.34 |
| 3/11/2022 | 131.82 |
| 3/18/2022 | 99.03 |
| 3/25/2022 | 91.77 |
| 4/1/2022 | 125.27 |
| 4/8/2022 | 108.34 |
| 4/15/2022 | 124.86 |
| 4/22/2022 | 119.66 |
| 4/29/2022 | 128.12 |
| 5/6/2022 | 128.4 |
| 5/13/2022 | 121.42 |
| 5/20/2022 | 114.61 |
| 5/27/2022 | 111.1 |
| 6/3/2022 | 98.48 |
| 6/10/2022 | 97.73 |
| 6/17/2022 | 114.23 |
| 6/24/2022 | 133.75 |
| 7/1/2022 | 127 |
| 7/8/2022 | 144.17 |
| 7/15/2022 | 145.25 |
| 7/22/2022 | 129.85 |
| 7/29/2022 | 123.7 |
| 8/5/2022 | 116.36 |
| 8/12/2022 | 122.58 |
| 8/19/2022 | 106.28 |
| 8/26/2022 | 123.81 |
| 9/2/2022 | 122.95 |
| 9/9/2022 | 120.72 |
| 9/16/2022 | 121.54 |
| 9/23/2022 | 124.95 |
| 9/30/2022 | 137.28 |
| 10/7/2022 | 141.89 |
| 10/14/2022 | 148.46 |
| 10/21/2022 | 152.89 |
| 10/28/2022 | 156.95 |
| 11/4/2022 | 144.6 |
| 11/11/2022 | 128.44 |
| 11/18/2022 | 111.69 |
| 11/25/2022 | 129.33 |
| 12/2/2022 | 129.6 |
| 12/9/2022 | 118.62 |
| 12/16/2022 | 132.79 |
| 12/23/2022 | 113.65 |
| 12/30/2022 | 113.17 |
| 1/6/2023 | 121.61 |
| 1/13/2023 | 113.87 |
| 1/20/2023 | 113.55 |
| 1/27/2023 | 114.76 |
| 2/3/2023 | 100.7 |
| 2/10/2023 | 98.99 |
| 2/17/2023 | 109.63 |
| 2/24/2023 | 110.11 |
| 3/3/2023 | 122.84 |
| 3/10/2023 | 122.52 |
| 3/17/2023 | 140.06 |
| 3/24/2023 | 180.11 |
| 3/31/2023 | 173.66 |
| 4/7/2023 | 135.93 |
| 4/14/2023 | 139.2 |
| 4/21/2023 | 118.84 |
| 4/28/2023 | 120.84 |
| 5/5/2023 | 122.46 |
| 5/12/2023 | 130.21 |
| 5/19/2023 | 120.52 |
| 5/26/2023 | 127.51 |
| 6/2/2023 | 145.37 |
| 6/9/2023 | 120.95 |
| 6/16/2023 | 115.77 |
| 6/23/2023 | 104.43 |
| 6/30/2023 | 105.74 |
| 7/7/2023 | 110.64 |
| 7/14/2023 | 130.41 |
| 7/21/2023 | 112.48 |
| 7/28/2023 | 106.66 |
| 8/4/2023 | 109.76 |
| 8/11/2023 | 115.91 |
| 8/18/2023 | 112.13 |
| 8/25/2023 | 120.51 |
| 9/1/2023 | 110.37 |
| 9/8/2023 | 102.92 |
| 9/15/2023 | 104.34 |
| 9/22/2023 | 96.61 |
| 9/29/2023 | 101.11 |
| 10/6/2023 | 113.55 |
| 10/13/2023 | 126.64 |
| 10/20/2023 | 128.33 |
| 10/27/2023 | 135.45 |
| 11/3/2023 | 129.16 |
| 11/10/2023 | 118.74 |
| 11/17/2023 | 116.79 |
| 11/24/2023 | 113.11 |
| 12/1/2023 | 107.43 |
| 12/8/2023 | 111.51 |
| 12/15/2023 | 121.65 |
| 12/22/2023 | 115.75 |
| 12/29/2023 | 111.38 |
| 1/5/2024 | 114.62 |
| 1/12/2024 | 116.19 |
| 1/19/2024 | 106.51 |
| 1/26/2024 | 104.97 |
| 2/2/2024 | 100.23 |
| 2/9/2024 | 106.72 |
| 2/16/2024 | 106.21 |
| 2/23/2024 | 109.2 |
| 3/1/2024 | 108.31 |
| 3/8/2024 | 106.48 |
| 3/15/2024 | 100.88 |
| 3/22/2024 | 97.82 |
| 3/29/2024 | 91.04 |
| 4/5/2024 | 86.38 |
| 4/12/2024 | 94.31 |
| 4/19/2024 | 112.82 |
| 4/26/2024 | 111.26 |
| 5/3/2024 | 104.4 |
| 5/10/2024 | 95.96 |
| 5/17/2024 | 94.23 |
| 5/24/2024 | 89.35 |
| 5/31/2024 | 83.57 |
| 6/7/2024 | 91.14 |
| 6/14/2024 | 91.82 |
| 6/21/2024 | 100.16 |
| 6/28/2024 | 94.09 |
| 7/5/2024 | 98.59 |
| 7/12/2024 | 98.78 |
| 7/19/2024 | 86.79 |
| 7/26/2024 | 94.29 |
| 8/2/2024 | 97.76 |
| 8/9/2024 | 112.26 |
| 8/16/2024 | 108.26 |
| 8/23/2024 | 102.81 |
| 8/30/2024 | 105.63 |
| 9/6/2024 | 107.77 |
| 9/13/2024 | 107.24 |
| 9/20/2024 | 100.6 |
| 9/27/2024 | 91 |
| 10/4/2024 | 92.53 |
| 10/11/2024 | 100.15 |
| 10/18/2024 | 118.47 |
| 10/25/2024 | 123.13 |
| 11/1/2024 | 128.4 |
| 11/8/2024 | 132.58 |
| 11/15/2024 | 99.85 |
| 11/22/2024 | 102.47 |
| 11/29/2024 | 99.14 |
| 12/6/2024 | 95.22 |
| 12/13/2024 | 83.2 |
| 12/20/2024 | 85.66 |
| 12/27/2024 | 91.75 |
| 1/3/2025 | 94.8 |
| 1/10/2025 | 93.35 |
| 1/17/2025 | 96.57 |
| 1/24/2025 | 95.6 |
| 1/31/2025 | 86.75 |
| 2/7/2025 | 91.76 |
| 2/14/2025 | 93.13 |
| 2/21/2025 | 84.67 |
| 2/28/2025 | 91.83 |
| 3/7/2025 | 104.46 |
| 3/14/2025 | 104.41 |
| 3/21/2025 | 101.01 |
| 3/28/2025 | 94.54 |
| 4/4/2025 | 96.83 |
| 4/11/2025 | 125.71 |
| 4/18/2025 | 137.26 |
| 4/25/2025 | 114.64 |
| 5/2/2025 | 105.79 |
| 5/9/2025 | 101.4 |
| 5/16/2025 | 100.4 |
| 5/23/2025 | 96.7 |
| 5/30/2025 | 100.91 |
| 6/6/2025 | 92.11 |
| 6/13/2025 | 89.65 |
| 6/20/2025 | 95.31 |
| 6/27/2025 | 90.1 |
| 7/4/2025 | 87.93 |
| 7/11/2025 | 86.09 |
| 7/18/2025 | 85.48 |
| 7/25/2025 | 83.29 |
| 8/1/2025 | 82.09 |
| 8/8/2025 | 83.83 |
| 8/15/2025 | 79.2 |
| 8/22/2025 | 76.66 |
| 8/29/2025 | 78.1 |
| 9/5/2025 | 79.39 |
| 9/12/2025 | 85.29 |
| 9/19/2025 | 73.37 |
| 9/26/2025 | 72.51 |
| 10/3/2025 | 74.38 |
| 10/10/2025 | 69.53 |
| 10/17/2025 | 81.65 |
| 10/24/2025 | 78.62 |
| 10/31/2025 | 68.94 |
| 11/7/2025 | 66.61 |
| 11/14/2025 | 74.41 |
| 11/21/2025 | 79.71 |
| 11/28/2025 | 78.81 |
| 12/5/2025 | 68.95 |
| 12/12/2025 | 67.28 |
| 12/19/2025 | 69.25 |
| 12/26/2025 | 59.41 |
| 1/2/2026 | 58.5 |
| 1/9/2026 | 62.36 |
| 1/16/2026 | 61.55 |
| 1/23/2026 | 58.05 |
| 1/30/2026 | 56.25 |
| 2/6/2026 | 59.2 |
| 2/13/2026 | 63.62 |
| 2/20/2026 | 70.1 |
| 2/27/2026 | 64.27 |
| 3/6/2026 | 73.38 |
| 3/13/2026 | 81.26 |
| 3/20/2026 | 91.17 |
| 3/27/2026 | 108.84 |
| 4/3/2026 | 111.95 |
| 4/10/2026 | 81.78 |
| 4/17/2026 | 72.15 |
| 4./24/2026 | 65.7 |
| 5/1/2026 | 66.97 |
| 5/8/2026 | 70.41 |
| 5/15/2026 | 67.25 |
| 5/22/2026 | 79.87 |
| 5/29/2026 | 78.43 |
| 6/5/2026 | 70.22 |
| 6/12/2026 | 75.2 |
| 6/19/2026 | 69.36 |
| 6/26/2026 | 65.39 |
| 7/3/2026 | 66.79 |
| 7/10/2026 | 65.4 |
| 7/17/2026 | 69.55 |
| 7/24/2026 | 70.88 |
| 7/31/2026 | 76.82 |
| 8/7/2026 | 83.02 |
| 8/14/2026 | 72.03 |
| 8/21/2026 | 69.58 |
| 8/28/2026 | 73.4 |
| 9/4/2026 | 70.97 |
| 9/11/2026 | 73.1 |
| 9/18/2026 | 82.21 |
| 9/25/2026 | 80.64 |
| 10/2/2026 | 96 |
| 10/9/2026 | 107.29 |
| 10/16/2026 | 98.47 |
| 10/23/2026 | 101.1 |
| 10/30/2026 | 103.31 |
| 11/6/2026 | 100.2 |
| 11/13/2026 | 92.77 |
| 11/20/2026 | 98.79 |
High-yield spreads improved but remain well above 300 bp, continuing to warrant caution. MOVE rose back toward 100. The configuration is consistent with a rates-driven sell-off rather than a broad improvement in risk appetite.
Expected 10yr ranges (by timeframe):
| Timeframe | Low (%) | High (%) |
|---|---|---|
| 1 week | 5.01 | 5.29 |
| 1 month | 4.86 | 5.44 |
| 1 year | 4.16 | 6.14 |
Implications & Positioning Lens
The sharp rise in intermediate yields has increased near-term discount-rate pressure. The 10Y at 5.15% now sits 65 bp above the 4.50% equity-valuation threshold (up from 36 bp the prior week) and remains below its recent high of 5.365%.
A forward P/E of 18.3 implies an earnings yield of approximately 5.46%. This still exceeds the 10Y by roughly 31 bp, so a modest positive equity risk premium remains. However, the premium has compressed meaningfully from the prior week (when the earnings yield was ~5.65% against a 4.86% 10Y). The compression has come almost entirely from the rise in the 10Y rather than from any material expansion in equity valuations.
This configuration is more nuanced than a simple “rates above equities” framing. Nominal yields have risen sharply while inflation compensation (5Y5Y5Y5Y forward rate provides a market-implied view of where policy ultimately settles once cyclical forces dissipate. Importantly, it captures the destination of policy rather than its near-term trajectory, and should be interpreted as a structural anchor rather than a tactical signal. More and 5Y breakeven) has been nearly unchanged, implying the bulk of the move has been in real rates and/or term premiumThe "extra" return investors demand for holding a long-term bond instead of a series of short-term ones. It acts as a safety buffer, compensating the lender for the increased risk that inflation or interest rates might change unexpectedly over a longer period. More. At the same time, HY OAS has improved 19 bp to 323 bp but remains well above 300 bp — a level that continues to signal caution on lower-quality credit even as investment-grade spreads have been more stable.
The combination of a now highly concentrated December +25 bp hike in FedWatch, elevated real-rate pressure in the belly, a compressed but still positive equity risk premium, and high-yield spreads that have not yet fully normalized argues for selectivity rather than broad risk-on or risk-off positioning. Quality durationBond Duration: Estimates the percentage change in a bond’s price for every 1% shift in interest rates. For example, a bond with a 3-year duration will gain or lose roughly ±3% of its value if rates fall or rise by 1%. More faces higher near-term pressure, while high-yield credit continues to require caution until spreads stabilize more convincingly below the 300 bp area.
Bottom Line
- Primary signal: Sharp belly-led sell-off with mixed curve geometry (longer spreads flattened, 10Y–3M steepened), accompanied by FedWatch locking in a December +25 bp hike.
- Policy: Near-term path is now highly concentrated on further tightening; later meetings show rising probability of larger moves.
- Risk: HY OAS improved but remains above 300 bp and is still a point of concern; MOVE rose.
- Unresolved: Whether the large nominal yield increase will be sustained if inflation compensation stays stable and high-yield spreads do not re-widen.
Positioning bias: quality durationBond Duration: Estimates the percentage change in a bond’s price for every 1% shift in interest rates. For example, a bond with a 3-year duration will gain or lose roughly ±3% of its value if rates fall or rise by 1%. More remains supported by lower intermediate yields and easing inflation compensation, but high-yield credit continues to require caution while spreads stay above 300 bp.
Summary Cheat-Sheet Table
| Metric | 13 Nov 2026 | Signal |
|---|---|---|
| Curve regime | Belly-led bear move | Mixed geometry (longer spreads flatter, 10Y–3M steeper) |
| 10Y–3M spread | ‘+83 bp | Widened |
| 30Y–2Y spread | ‘+59 bp | Flattened |
| 10Y vs 4.50% threshold | ‘+65 bp | Elevated |
| FedWatch Dec meeting | ~94% +25 bp | Highly concentrated |
| HY OAS | 323 bp | Improved but still >300 bp — concern |
| MOVE | 98.79 | Higher |
| 5Y5Y5Y5Y forward rate provides a market-implied view of where policy ultimately settles once cyclical forces dissipate. Importantly, it captures the destination of policy rather than its near-term trajectory, and should be interpreted as a structural anchor rather than a tactical signal. More / 5Y BEI | 2.18% / 2.30% | Nearly unchanged |
Yield Curve Data
| Date | 3-mth | 6-mth | 1-yr | 2-yr | 5-yr | 10-yr | 30-yr | AaaAaa represents the highest rung of investment-grade corporate debt, indicating top-level creditworthiness and the lowest default risk. More | BaaBaa represent the lowest rung of investment-grade corporate debt with moderate credit risk, making them susceptible to higher default risk than Aaa bonds. More | HY-OAS | 5Y5Y5Y5Y forward rate provides a market-implied view of where policy ultimately settles once cyclical forces dissipate. Importantly, it captures the destination of policy rather than its near-term trajectory, and should be interpreted as a structural anchor rather than a tactical signal. More Forward | 5Y Breakeven Inflation | MOVE IndexThe ICE Bank of America U.S. Bond Market Option Volatility Estimate (MOVE) Index measures implied volatility of U.S. Treasury yields, derived from options on Treasuries (primarily 2Y–30Y maturities). It’s commonly called the “VIX for bonds”, but more precisely, it reflects the market’s expectation of how much Treasury yields will move, not bond prices. It is a critical cross-asset signal. More | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 11/13/2026 | 4.32 | 4.42 | 4.65 | 4.88 | 4.98 | 5.15 | 5.47 | 6.17 | 6.62 | 3.23 | 2.18 | 2.3 | 98.79 | |
| 11/6/2026 | 4.19 | 4.23 | 4.33 | 4.51 | 4.64 | 4.86 | 5.26 | 5.99 | 6.42 | 3.42 | 2.17 | 2.29 | 92.77 | |
| 10/30/2026 | 4.16 | 4.25 | 4.36 | 4.56 | 4.71 | 4.94 | 5.31 | 6.01 | 6.47 | 3.44 | 2.22 | 2.46 | 100.20 | |
| 10/23/2026 | 4.22 | 4.30 | 4.44 | 4.69 | 4.82 | 5.00 | 5.33 | 6 | 6.47 | 3.38 | 2.2 | 2.48 | 103.31 | |
| 10/16/2026 | 4.26 | 4.34 | 4.46 | 4.74 | 4.89 | 5.09 | 5.43 | 6.06 | 6.55 | 3.31 | 2.33 | 2.37 | 101.10 | |
| 10/9/2026 | 4.25 | 4.32 | 4.47 | 4.80 | 5.02 | 5.24 | 5.60 | 6.22 | 6.69 | 3.11 | 2.32 | 2.34 | 98.47 | |
| 10/2/2026 | 4.19 | 4.27 | 4.46 | 4.83 | 5.06 | 5.28 | 5.63 | 6.28 | 6.75 | 3.10 | 2.35 | 2.37 | 107.29 | |
| 9/25/2026 | 4.24 | 4.33 | 4.50 | 4.81 | 4.98 | 5.17 | 5.49 | 6.18 | 6.63 | 2.93 | 2.34 | 2.34 | 96.00 | |
| 9/18/2026 | 4.14 | 4.24 | 4.44 | 4.76 | 4.86 | 5.01 | 5.34 | 5.98 | 6.41 | 2.68 | 2.35 | 2.31 | 80.64 | |
| 9/11/2026 | 4.07 | 4.12 | 4.35 | 4.63 | 4.78 | 4.96 | 5.35 | 6.03 | 6.46 | 2.65 | 2.32 | 2.4 | 82.21 | |
| 9/4/2026 | 3.91 | 3.98 | 4.13 | 4.37 | 4.54 | 4.78 | 5.24 | 5.92 | 6.34 | 2.68 | 2.33 | 2.37 | 73.1 | |
| 8/28/2026 | 3.90 | 4.02 | 4.15 | 4.34 | 4.48 | 4.73 | 5.22 | 5.86 | 6.27 | 2.60 | 2.32 | 2.3 | 70.97 | |
| 8/21/2026 | 3.88 | 3.95 | 4.03 | 4.24 | 4.43 | 4.74 | 5.27 | 5.92 | 6.37 | 2.70 | 2.34 | 2.34 | 73.4 | |
| 8/14/2026 | 3.86 | 3.95 | 3.98 | 4.17 | 4.36 | 4.68 | 5.25 | 5.92 | 6.37 | 2.67 | 2.3 | 2.24 | 69.58 | |
| 8/7/2026 | 3.87 | 3.96 | 4.01 | 4.19 | 4.35 | 4.65 | 5.19 | 5.85 | 6.29 | 2.7 | 2.28 | 2.22 | 72.03 | |
| 7/31/2026 | 3.83 | 3.98 | 4.08 | 4.28 | 4.45 | 4.75 | 5.27 | 5.96 | 6.38 | 2.84 | 2.3 | 2.26 | 83.02 | |
| 7/24/2026 | 3.96 | 4.08 | 4.14 | 4.33 | 4.43 | 4.69 | 5.16 | 5.87 | 6.28 | 2.79 | 2.28 | 2.24 | 76.82 | |
| 7/17/2026 | 3.85 | 3.96 | 4.01 | 4.18 | 4.28 | 4.55 | 5.06 | 5.72 | 6.14 | 2.73 | 2.21 | 2.27 | 70.88 | |
| 7/10/2026 | 3.85 | 3.99 | 4.06 | 4.21 | 4.30 | 4.56 | 5.06 | 5.72 | 6.14 | 2.69 | 2.2 | 2.28 | 69.55 | |
| 7/3/2026 | 3.82 | 3.98 | 3.96 | 4.14 | 4.23 | 4.49 | 4.98 | 5.6 | 6.02 | 2.74 | 2.22 | 2.24 | 65.4 | |
| 6/26/2026 | 3.83 | 3.94 | 3.94 | 4.07 | 4.12 | 4.38 | 4.87 | 5.5 | 5.94 | 2.83 | 2.19 | 2.21 | 66.79 | |
| 6/19/2026 | 3.83 | 3.92 | 4.00 | 4.19 | 4.23 | 4.46 | 4.90 | 5.5 | 5.97 | 2.66 | 2.23 | 2.27 | 65.39 | |
| 6/12/2026 | 3.78 | 3.82 | 3.86 | 4.09 | 4.21 | 4.48 | 4.97 | 5.52 | 6.01 | 2.71 | 2.23 | 2.39 | 69.36 | |
| 6/5/2026 | 3.78 | 3.81 | 3.88 | 4.17 | 4.29 | 4.55 | 5.01 | 5.53 | 6.06 | 2.76 | 2.24 | 2.48 | 75.2 | |
| 5/29/2026 | 3.69 | 3.78 | 3.79 | 3.98 | 4.13 | 4.45 | 4.99 | 5.5 | 6.02 | 2.72 | 2.24 | 2.52 | 70.22 | |
| 5/22/2026 | 3.68 | 3.79 | 3.86 | 4.13 | 4.27 | 4.56 | 5.07 | 5.61 | 6.13 | 2.74 | 2.26 | 2.54 | 78.43 | |
| 5/15/2026 | 3.69 | 3.77 | 3.82 | 4.09 | 4.26 | 4.59 | 5.12 | 5.65 | 6.21 | 2.80 | 2.28 | 2.7 | 79.87 | |
| 5/8/2026 | 3.69 | 3.74 | 3.75 | 3.90 | 4.02 | 4.38 | 4.95 | 5.47 | 6.03 | 2.81 | 2.28 | 2.62 | 67.25 | |
| 5/1/2026 | 3.68 | 3.71 | 3.73 | 3.88 | 4.02 | 4.39 | 4.97 | 5.49 | 6.08 | 2.77 | 2.27 | 2.69 | 70.41 | |
| 4/24/2026 | 3.69 | 3.71 | 3.67 | 3.78 | 3.92 | 4.31 | 4.91 | 5.41 | 6.01 | 2.86 | 2.23 | 2.61 | 66.97 | |
| 4/17/2026 | 3.70 | 3.69 | 3.64 | 3.71 | 3.84 | 4.26 | 4.88 | 5.36 | 5.98 | 2.83 | 2.16 | 2.56 | 65.7 | |
| 4/10/2026 | 3.69 | 3.72 | 3.70 | 3.81 | 3.94 | 4.31 | 4.91 | 5.42 | 6.03 | 2.94 | 2.14 | 2.58 | 72.15 | |
| 4/3/2026 | 3.71 | 3.73 | 3.72 | 3.84 | 3.99 | 4.35 | 4.91 | 5.44 | 6.05 | 3.13 | 2.11 | 2.61 | 81.78 | |
| 3/27/2026 | 3.73 | 3.75 | 3.77 | 3.88 | 4.06 | 4.44 | 4.98 | 5.66 | 6.22 | 3.42 | 2.06 | 2.56 | 111.95 | |
| 3/20/2026 | 3.74 | 3.79 | 3.80 | 3.88 | 4.01 | 4.39 | 4.96 | 5.61 | 6.18 | 3.24 | 2.13 | 2.63 | 108.84 | |
| 3/13/2026 | 3.72 | 3.70 | 3.66 | 3.73 | 3.87 | 4.28 | 4.90 | 5.60 | 6.11 | 3.28 | 2.11 | 2.61 | 91.17 | |
| 3/6/2026 | 3.71 | 3.68 | 3.56 | 3.53 | 3.67 | 4.10 | 4.73 | 5.32 | 5.86 | 3.13 | 2.14 | 2.56 | 81.26 | |
| 2/27/2026 | 3.68 | 3.61 | 3.48 | 3.42 | 3.58 | 4.02 | 4.64 | 5.25 | 5.77 | 3.10 | 2.1 | 2.40 | 73.38 | |
| 2/20/2026 | 3.69 | 3.60 | 3.51 | 3.46 | 3.65 | 4.08 | 4.72 | 5.25 | 5.76 | 2.86 | 2.13 | 2.43 | 64.27 | |
| 2/13/2026 | 3.68 | 3.59 | 3.42 | 3.40 | 3.61 | 4.04 | 4.69 | 5.31 | 5.81 | 2.95 | 2.12 | 2.42 | 70.1 | |
| 2/6/2026 | 3.68 | 3.59 | 3.45 | 3.54 | 3.80 | 4.26 | 4.85 | 5.40 | 5.90 | 2.87 | 2.18 | 2.50 | 63.62 | |
| 1/30/2026 | 3.67 | 3.61 | 3.48 | 3.54 | 3.81 | 4.24 | 4.87 | 5.35 | 5.86 | 2.80 | 2.19 | 2.53 | 59.2 |
Source: Federal Reserve Economic Data (FRED) is an online database created and maintained by the Research Department at the Federal Reserve Bank of St. Louis